Aerial view of a newly installed shingle roof on a Central Connecticut home

Insurance claim guide / Connecticut

Working with your insurance carrier on a roof claim.

What to document, how adjusters work, what supplements are, and what we can or can't promise.

Prefer to call? (959) 248-2441

  • Family-owned
  • GAF Certified
  • CT Reg #0017287

What we can't promise.We can't guarantee your carrier approves the claim. We can't promise a specific settlement amount. We don't pay your deductible. What we DO is provide thorough contractor documentation that supports a clean carrier conversation.

Last updated:

Tim North · GAF Certified Roofer · Roofing & exterior systems
Storm-worn roof documented for a Connecticut insurance claim

Storm documentation

Start with visible conditions.

Insurance work needs clear photos, careful notes, and a clean scope conversation.

The 6-step claim process

Damage to repair: roughly how it unfolds.

Every claim varies, but the rough process is consistent.

Six steps

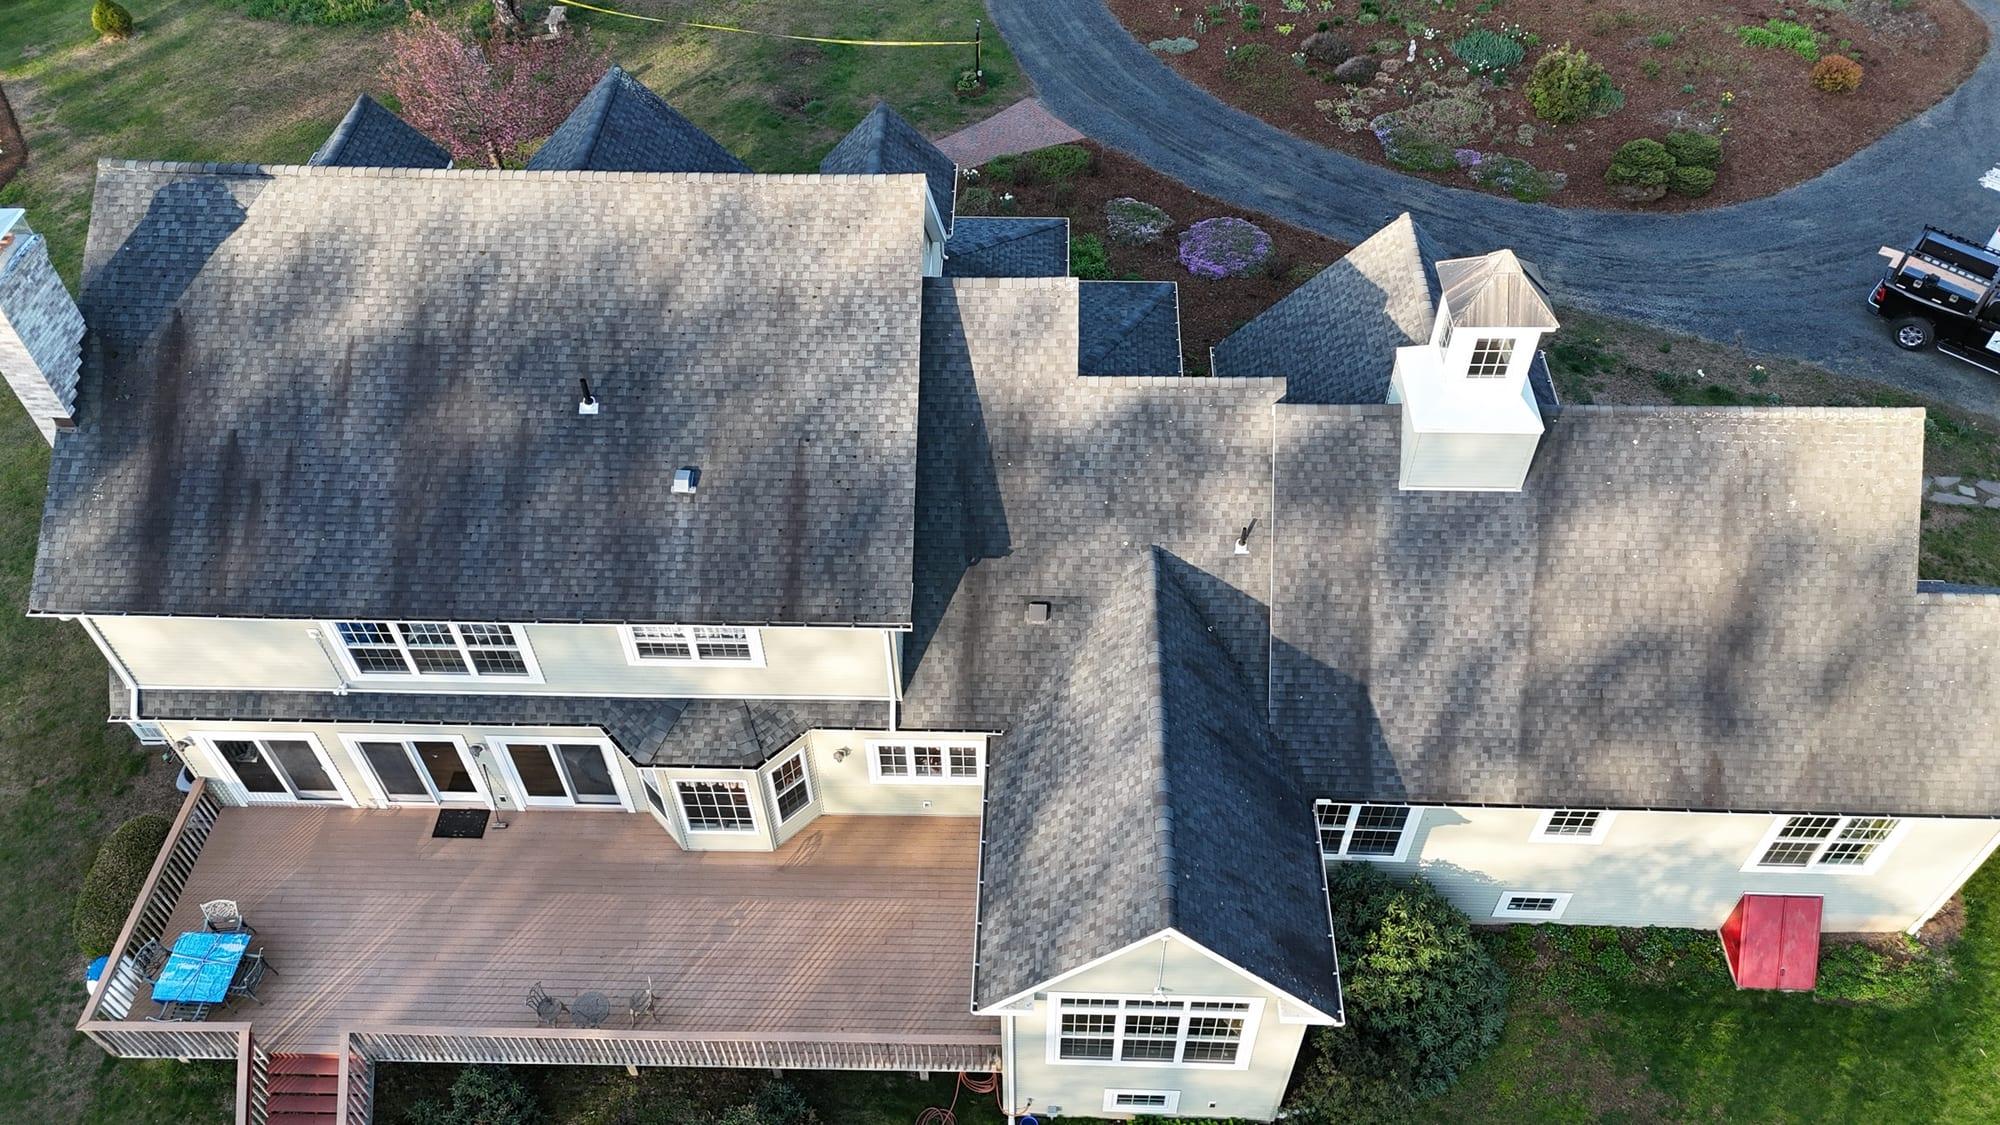
Central Connecticut home exterior documented for a roof insurance claim
  1. Damage occurs

    Damage appears. Document first. Do not sign.

  2. Document everything

    Photograph damage and keep records together.

  3. Contact your carrier

    Open the claim. Call us for contractor documentation.

  4. Adjuster inspection

    The adjuster visits. We can document damage.

  5. Settlement

    The carrier usually issues ACV first.

  6. Repair execution

    We do the work. Tim documents supplements.
Adjuster terminology

Six terms worth understanding before the inspection.

The carrier uses specific language. These terms keep you in the conversation.

Standing-seam metal roof on a Central Connecticut home
ACV (Actual Cash Value)
Depreciated value of the damaged roof.
RCV (Replacement Cost Value)
New-roof cost before depreciation.
Depreciation
The wear deduction. Recoverable depreciation returns after completed work.
Supplement
A documented add-on found during work.
Scope of loss
The adjuster's written damage and coverage scope.
Deductible
Your out-of-pocket claim portion. Waiving it is fraud in Connecticut.

Common pitfalls

Five contractor red flags that should send you elsewhere.

  • Storm-chaser contractors

    Out-of-state contractors appear after storms, then disappear.

  • 'Deductible waiver' offers

    Connecticut prohibits this. Deductible-waiver offers start with fraud.

  • Same-day contracts

    Insurance claims do not require a same-day signature. Pressure is the warning sign.

  • Cash-only deals

    Legitimate contractors invoice through standard channels.

  • Promising claim approval

    The carrier decides approval. We promise documentation, not approval.

Gallery

What we document on a claim assessment

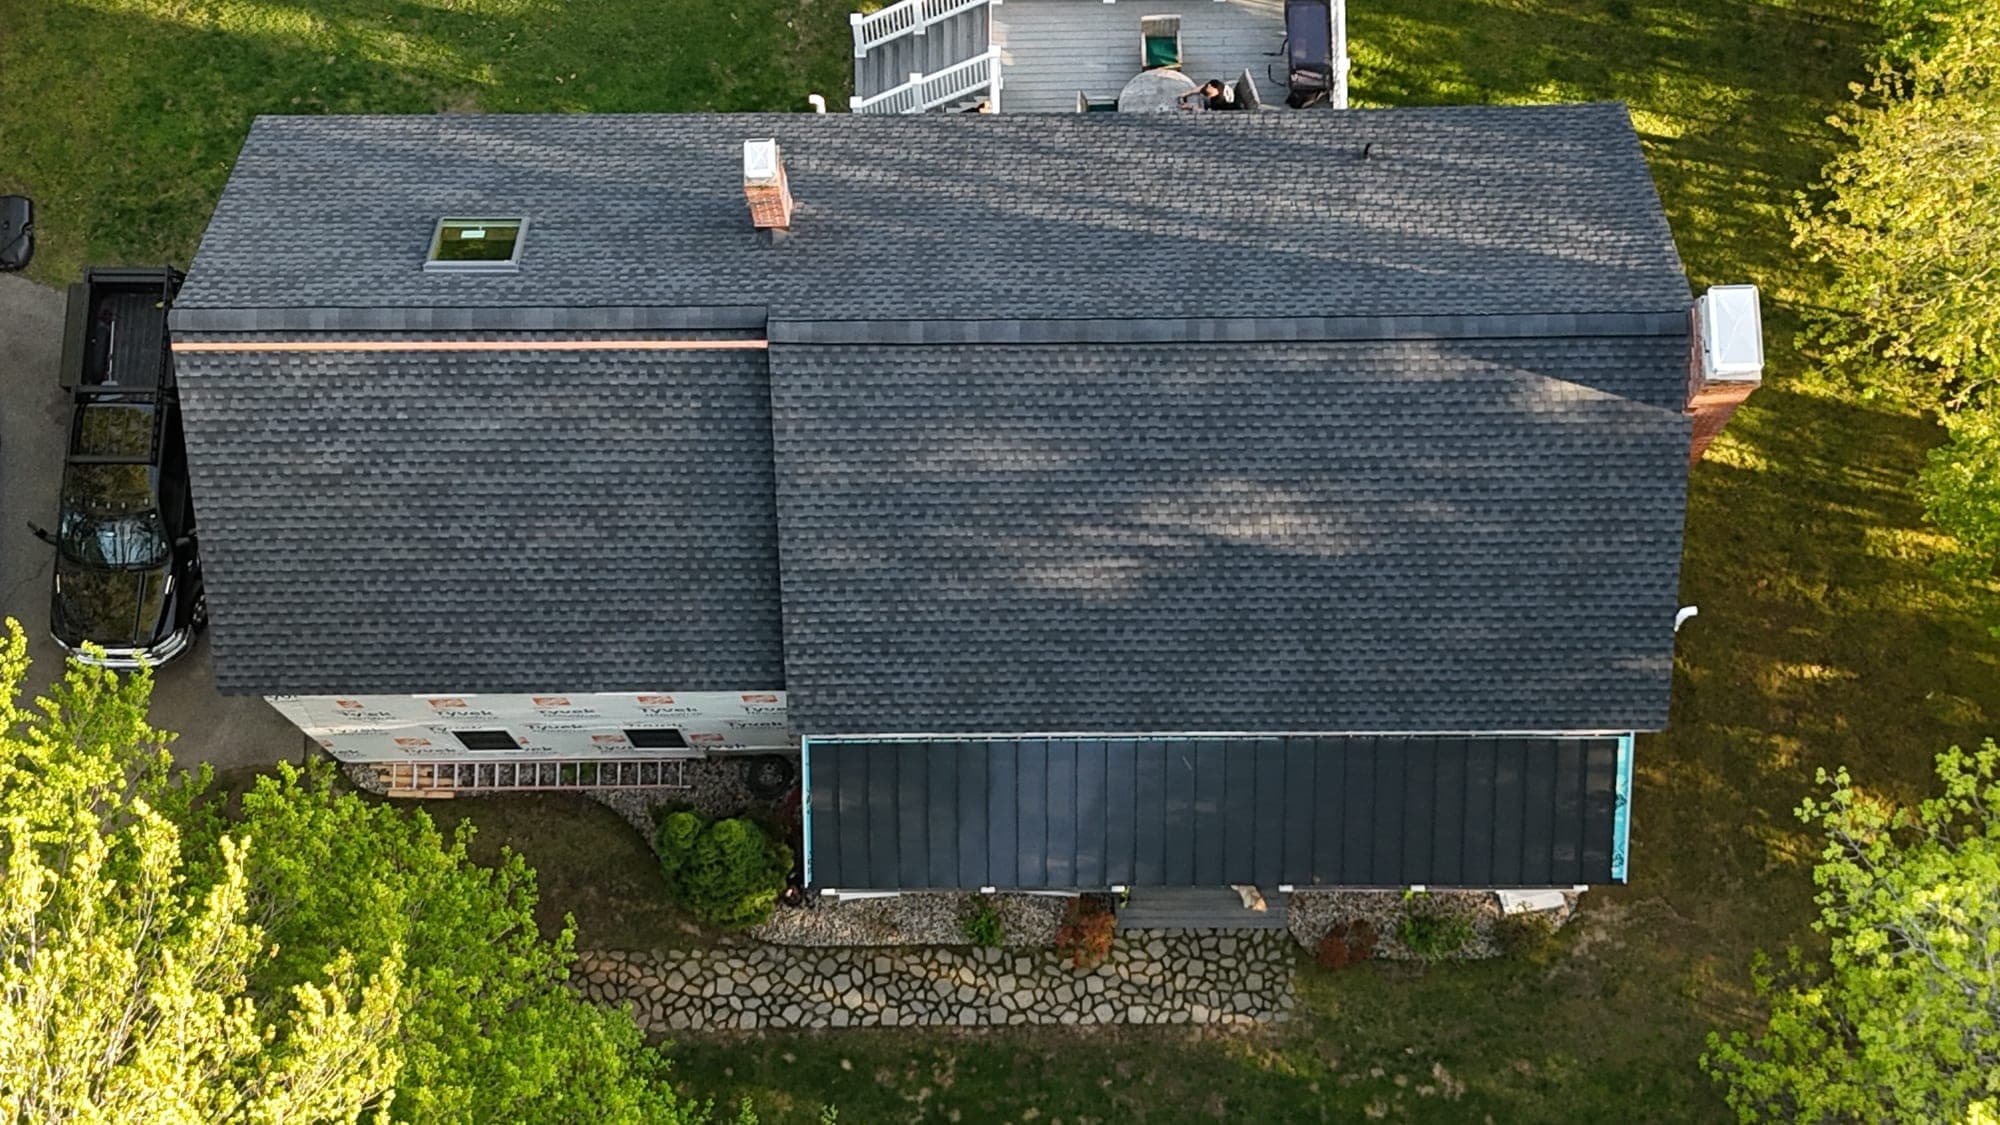
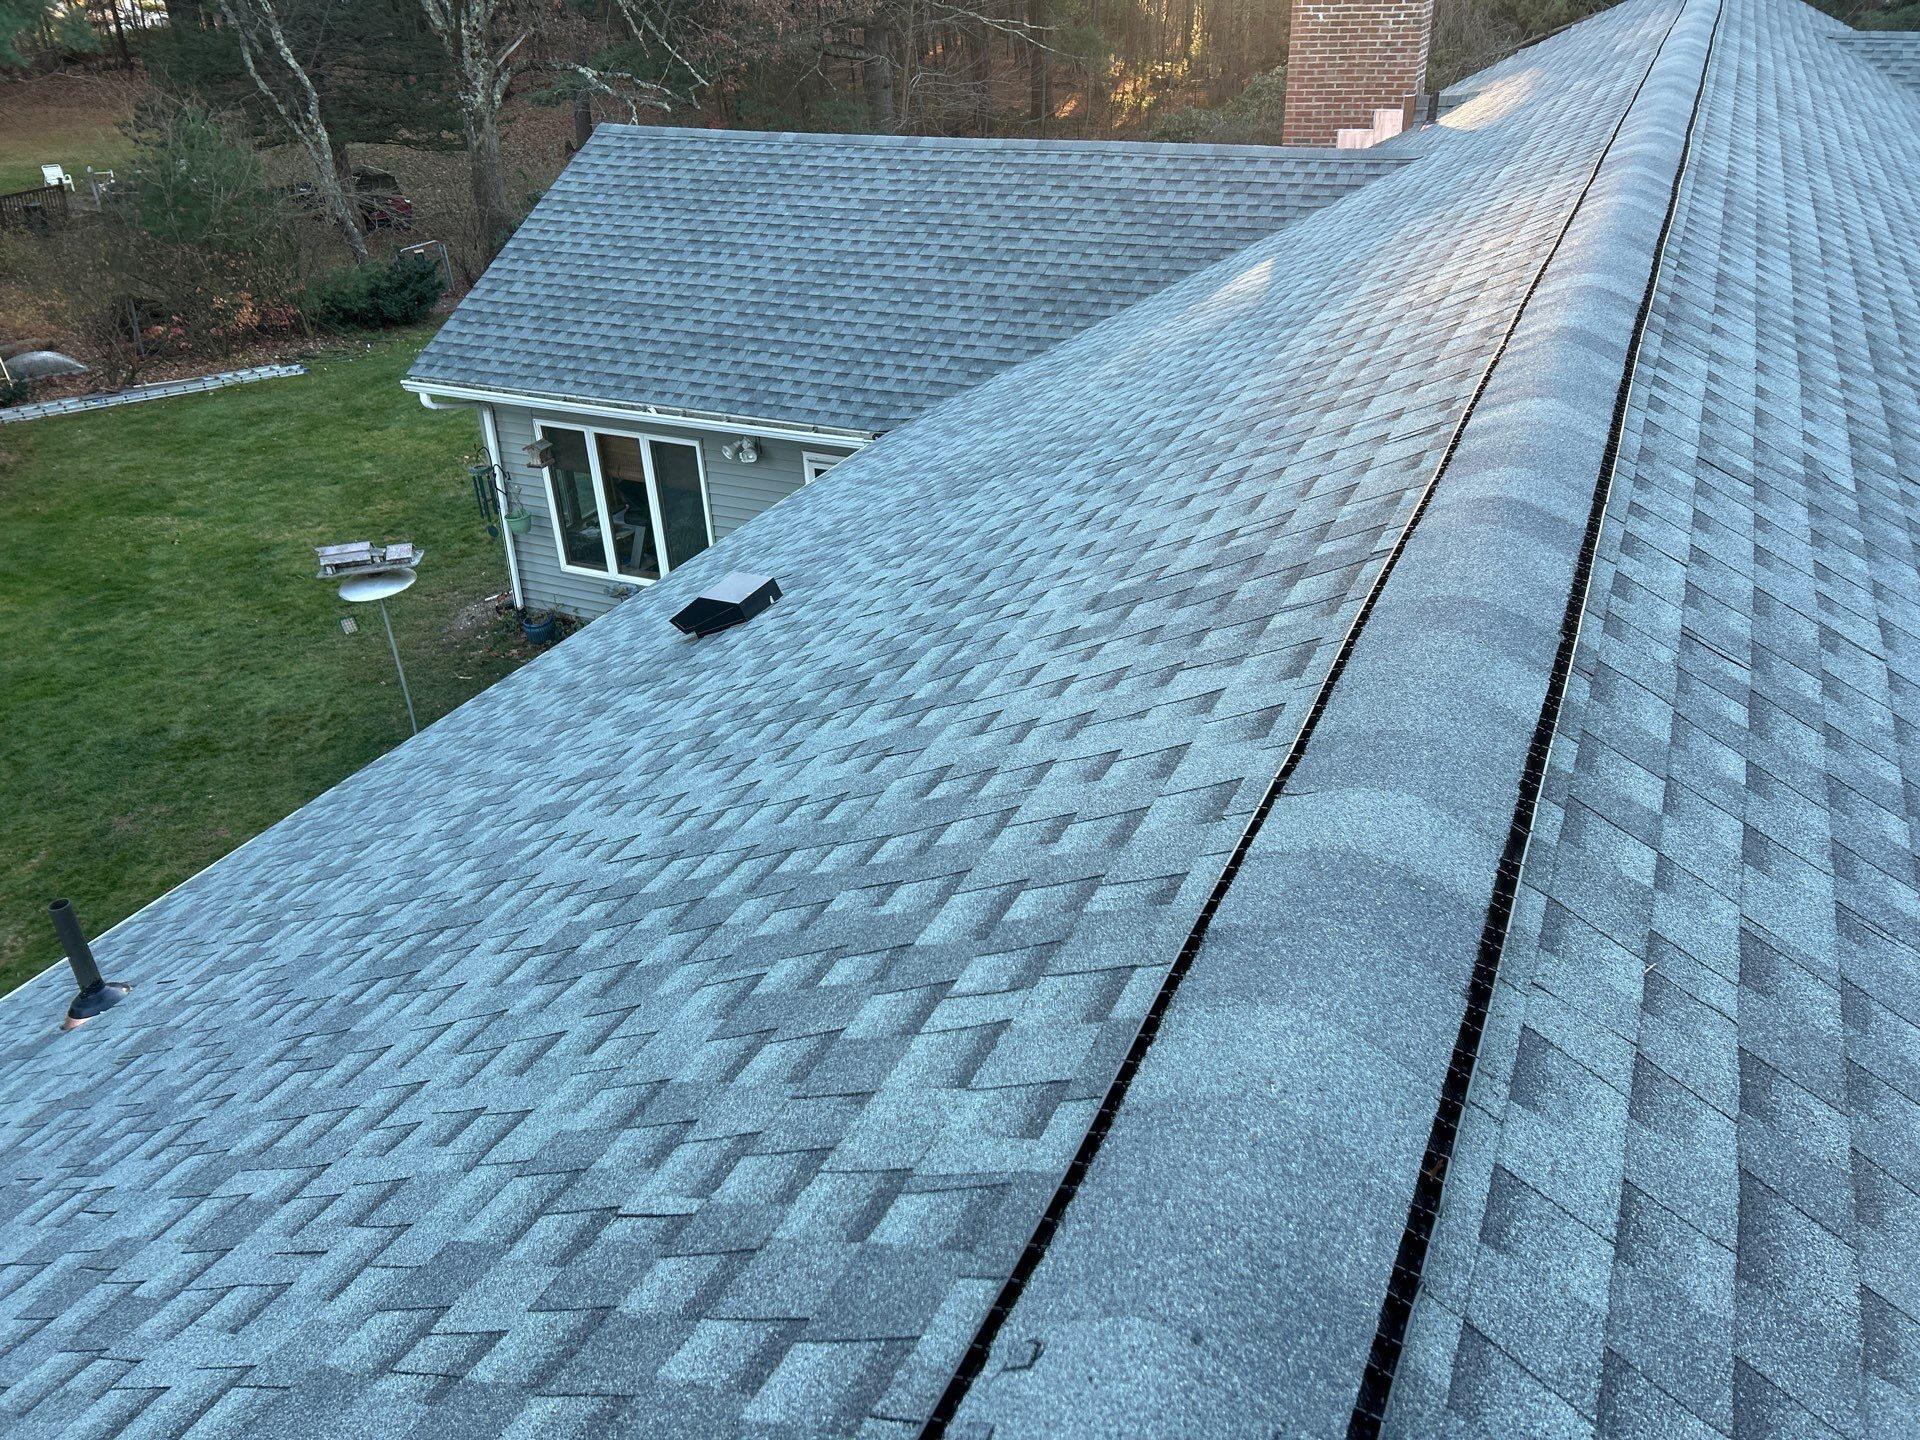
Finished shingle roof and flashing detail on a Central Connecticut home
Finished roof
Finished siding and trim on a Central Connecticut home
Siding and trim
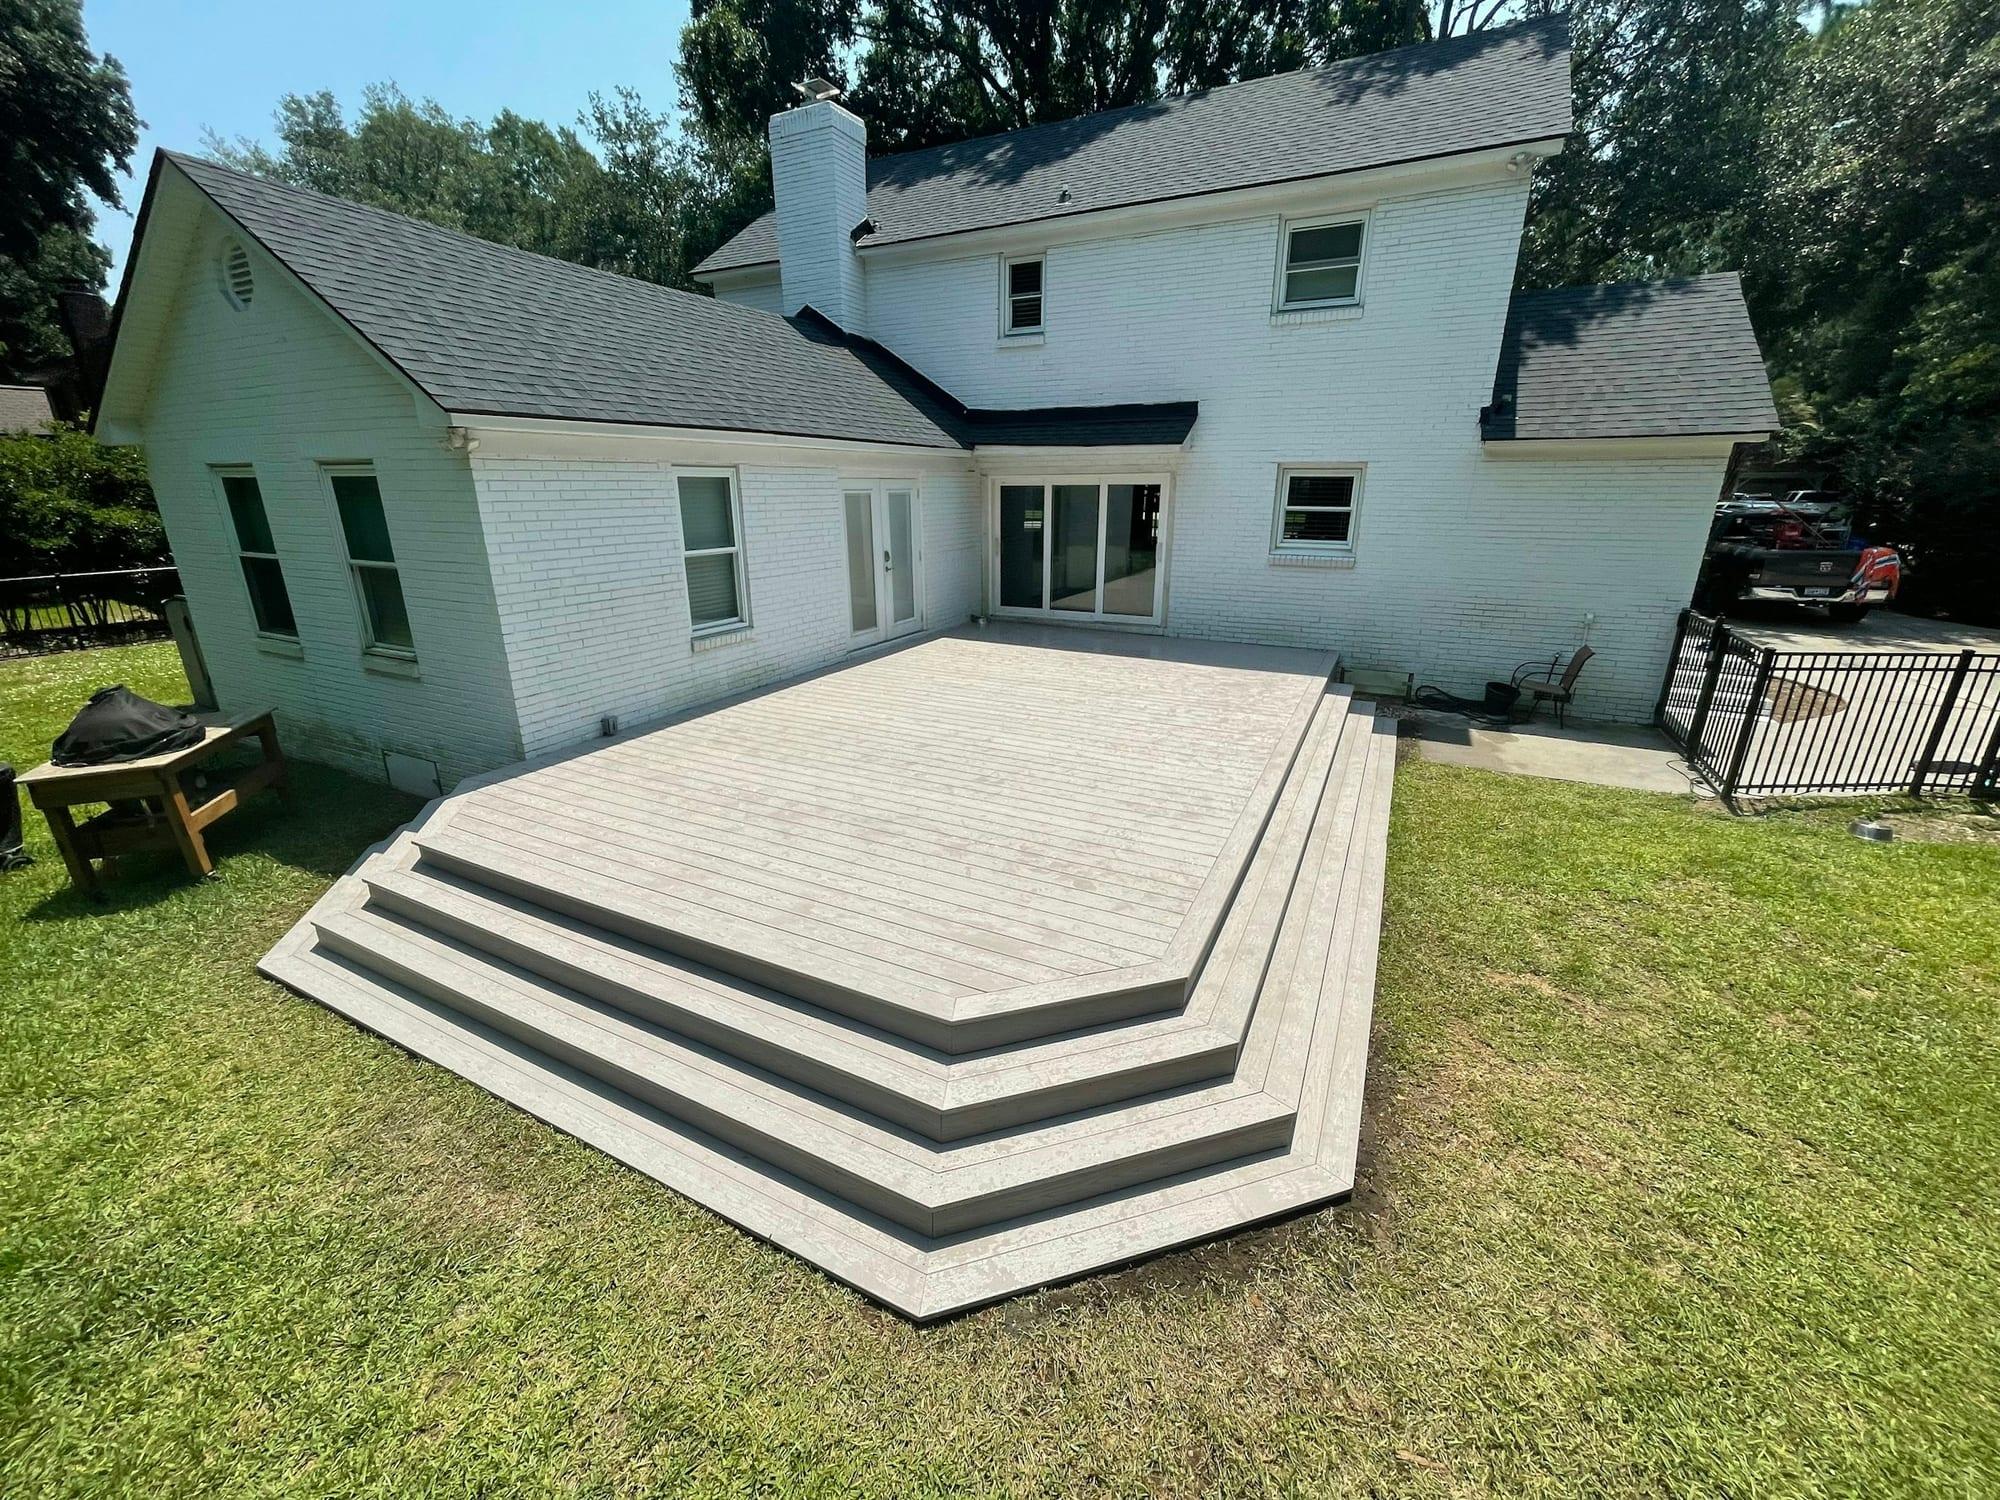
Composite deck and outdoor structure on a Central Connecticut home
Deck and terrace
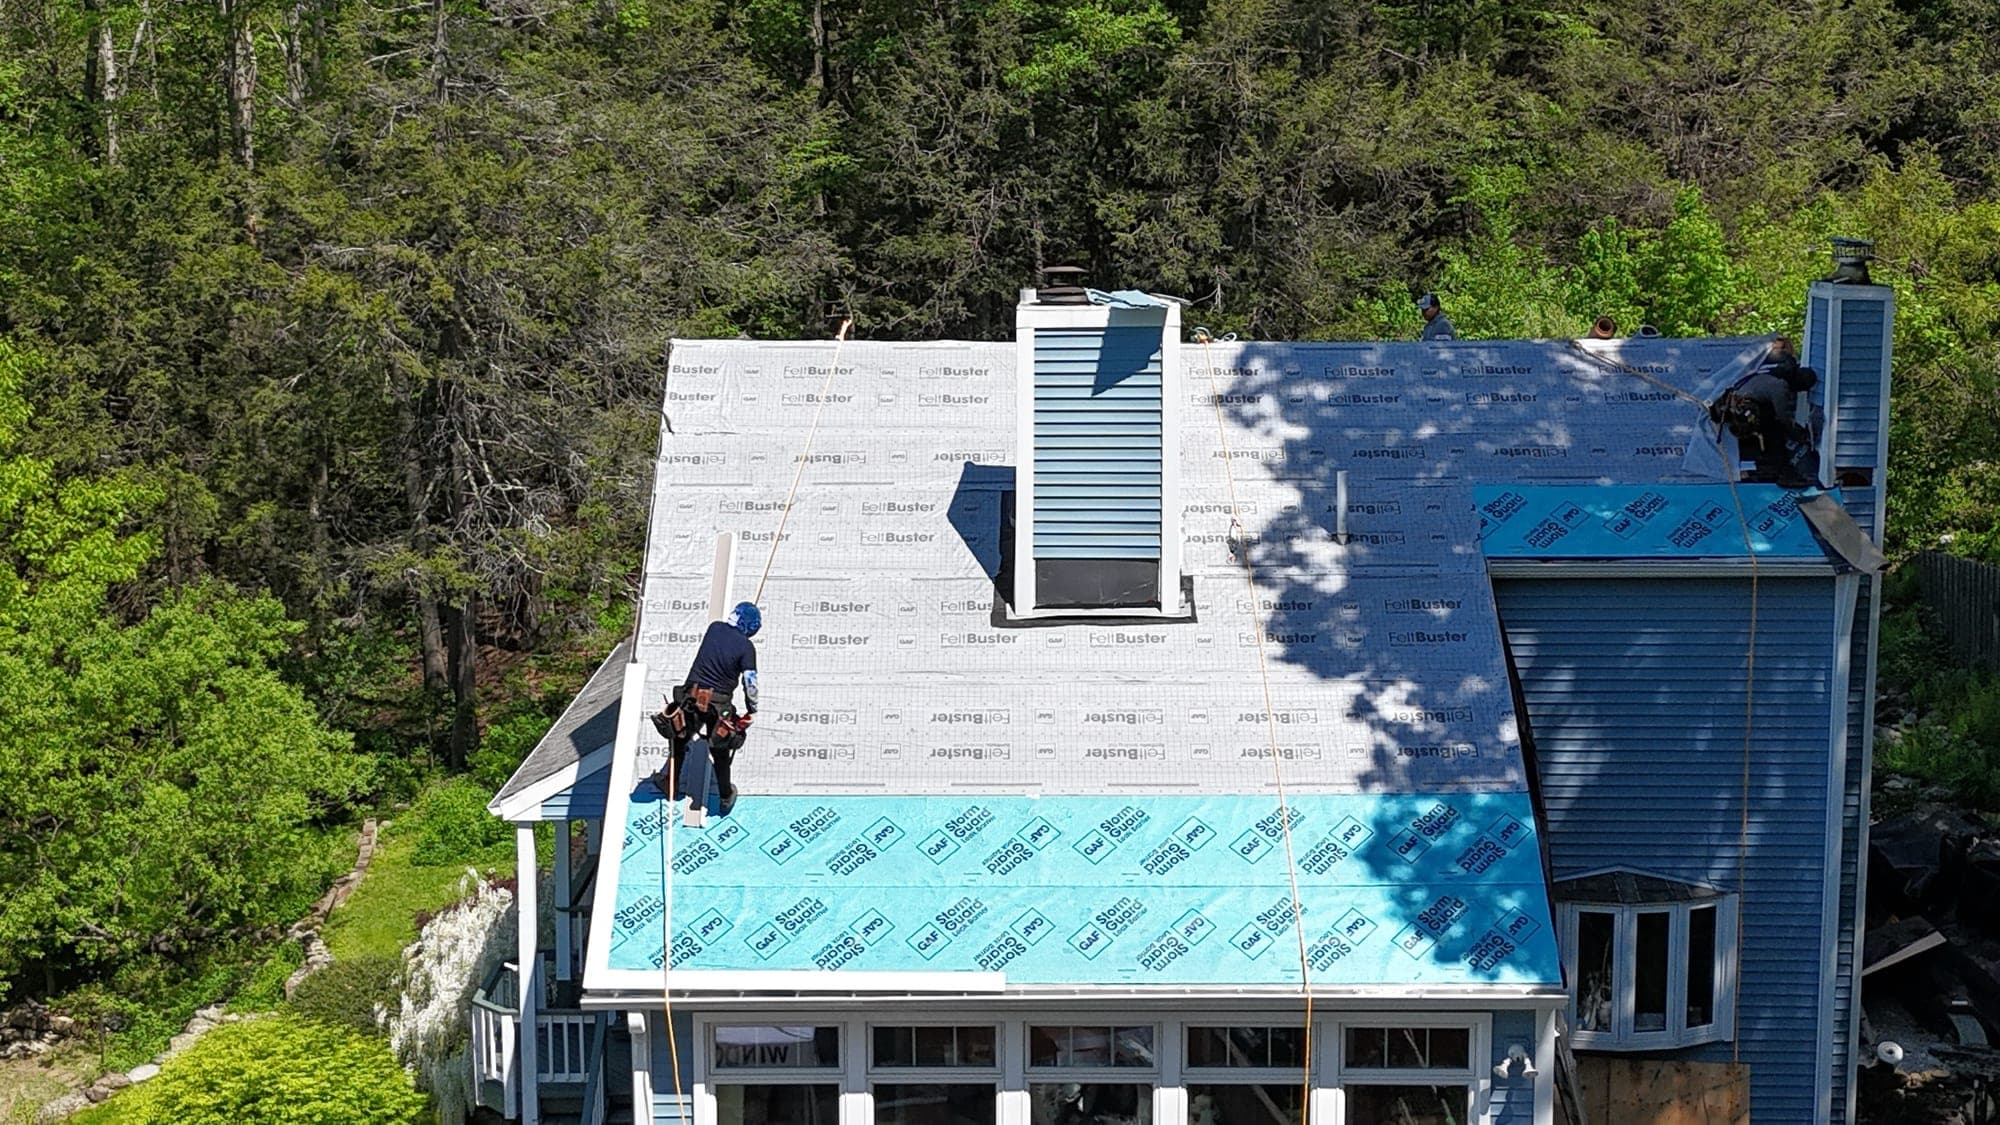
Roof underlayment, flashing, and deck work on a Central Connecticut home

Exterior repair sequence

Scope the exterior as one system.

Damage at one edge can affect flashing, trim, gutters, siding, or openings.

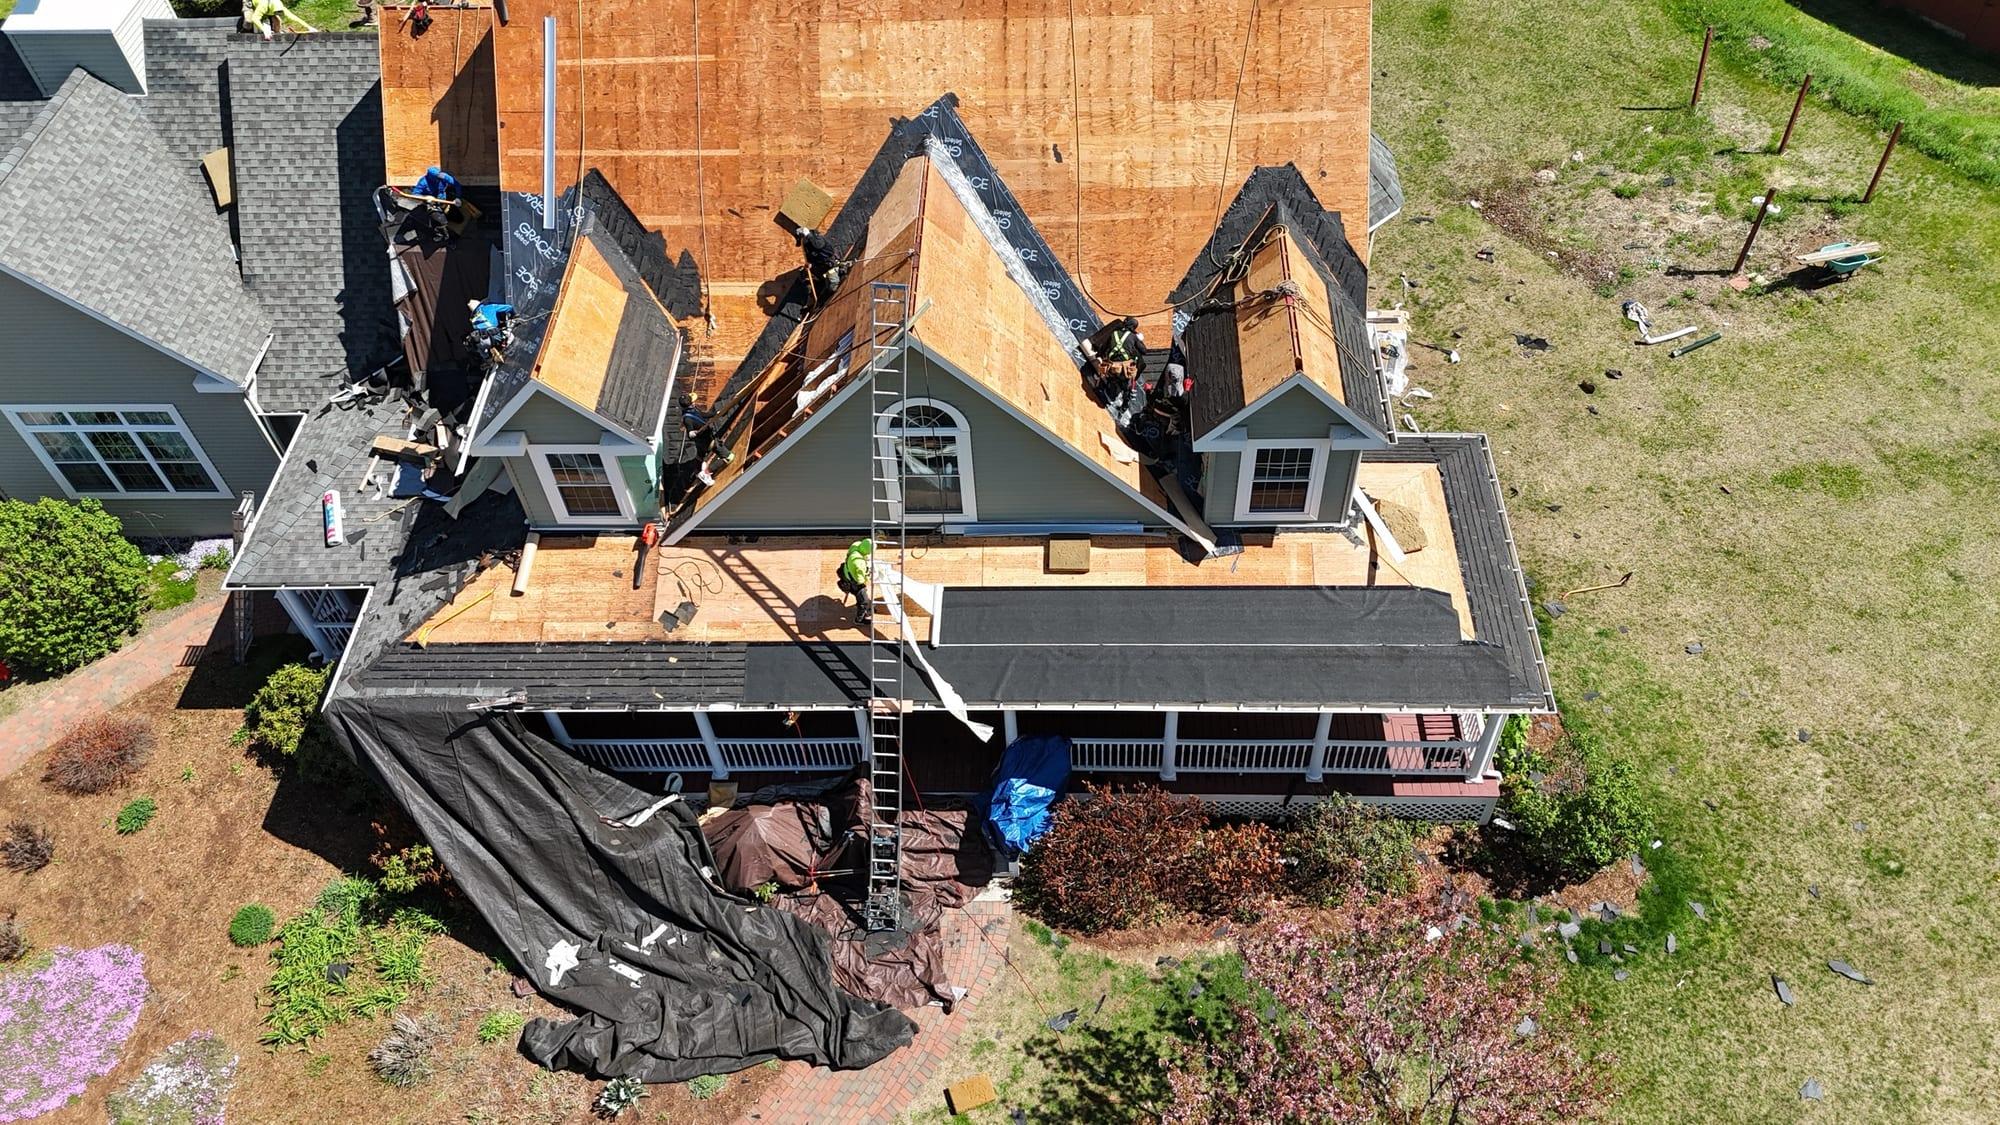
Northern Limits crew replacing a storm-damaged roof in Central Connecticut

Documented repair work

Every repair is photographed and documented for a clean carrier conversation.

Common questions

Insurance roof claim questions homeowners ask.

Practical answers about our contractor role through a claim.

Talk to Northern Limits

We document the work. The carrier handles the claim.

Contractor-side documentation that supports a clean carrier conversation.

Request a Quote